
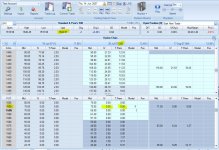
I've started backtesting in 2007 with ONE and I have issues with the data. Please take a look at the "Capture" screenshot. This is roughly 1% ITM/week compounded geometrically and there's no extrinsic value showing. In fact, there are is a range of strikes there with no extrinsic value. Zero. That doesn't feel right to me--even DITM--with four weeks to expiration.
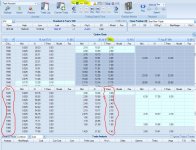
If you look OTM, in the "Capture3" screenshots, puts have extrinsic value well into the 3rd SD.
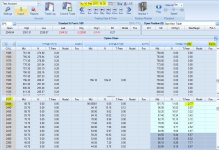
Now look at the "Capture2" screenshot from 2017. There's a much more reasonable distribution of extrinsic value across these options. That, to me, feels right.
I used to use OV and I'd sometimes have the same issue with their data. It didn't seem to be every day, certainly, but before 2008-9 or so, it did seem somewhat prevalent.
What might be going on here?
If you look OTM, in the "Capture3" screenshots, puts have extrinsic value well into the 3rd SD.
Now look at the "Capture2" screenshot from 2017. There's a much more reasonable distribution of extrinsic value across these options. That, to me, feels right.
I used to use OV and I'd sometimes have the same issue with their data. It didn't seem to be every day, certainly, but before 2008-9 or so, it did seem somewhat prevalent.
What might be going on here?
Attachments
Last edited:
