I while ago Dan Harvey described a way he hedges his portfolio by using a butterfly. He also adds a long put, but let’s have a look at the butterfly.
Here are his guidelines:
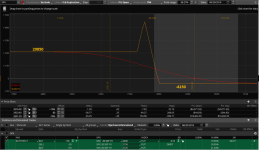
I placed one in TOS to see how it looks. This is 31 DTE, but this should not matter for now.
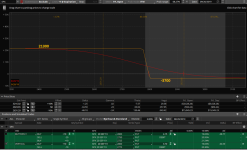
My question is: why can’t we use a simple put debit spread for the same purpose? I set this one in TOS for roughly the same break even and it costs a bit less, involves fewer trades and even P/L at expiration looks a bit better.
What makes the butterfly a better choice?
Thank you,
Michael
Here are his guidelines:
- 20 to 28 days to expiration
- Short butterfly strike is 5% to 7.5% below the market
- Upper long strike is 50 points above the short strike
- Lower long strike is 25 points below the short strike
I placed one in TOS to see how it looks. This is 31 DTE, but this should not matter for now.
My question is: why can’t we use a simple put debit spread for the same purpose? I set this one in TOS for roughly the same break even and it costs a bit less, involves fewer trades and even P/L at expiration looks a bit better.
What makes the butterfly a better choice?
Thank you,
Michael