today in tg1, someone mentioned that most of the market returns occur overnight. i read this study
last year and decided to prove or disprove it myself. as with all market performance statistics, it depends
on when you start measuring. my conclusion is it's true and not true. i couldn't locate my spreadsheet
during the meeting but i'm including it here for those who want to slice and dice it further.
i used spy for the market returns and started my analysis jan 2000. i don't recall the time frame in the article,
but 2000 seemed like a good starting point to me. from 2000 till 2018 it's true. practically all the market
returns happened overnight. but things changed in 2009. starting then it's been somewhat mixed.
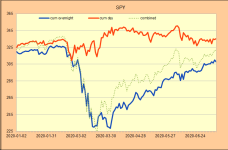
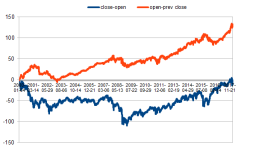
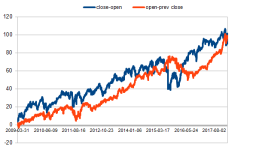
the below graphs separate ovenight performance and day only performance. the red line is overnight
and the blue is from open to close during the day the first graph starts in jan 2000, the second starts
in 2009.
last year and decided to prove or disprove it myself. as with all market performance statistics, it depends
on when you start measuring. my conclusion is it's true and not true. i couldn't locate my spreadsheet
during the meeting but i'm including it here for those who want to slice and dice it further.
i used spy for the market returns and started my analysis jan 2000. i don't recall the time frame in the article,
but 2000 seemed like a good starting point to me. from 2000 till 2018 it's true. practically all the market
returns happened overnight. but things changed in 2009. starting then it's been somewhat mixed.
the below graphs separate ovenight performance and day only performance. the red line is overnight
and the blue is from open to close during the day the first graph starts in jan 2000, the second starts
in 2009.