Thanks for looking into it.
1. I don't think it is a matter of misspricing.
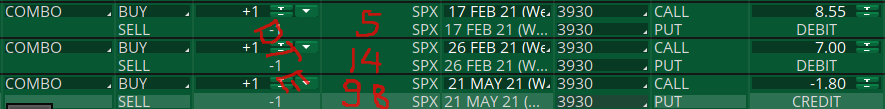
Put and call prices in the chains look pretty much OK. Also a glance at how combo prices changes with dte, do not rise misspricing alert.
2. I don't know the model you are using.
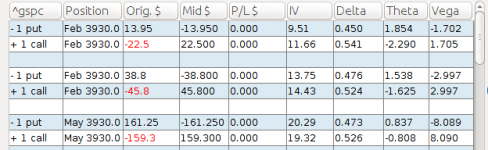
Seems that there are some limitations in it because you have different put and call IV - where in 'reality', means with decent model, they should be close to the same. That doesn't mean your model is "wrong", I also use very much imperfect model, just I know what to expect of mine and what not to. I do not know yours.
My thought is that the cause of decreasing prices with dte are due to dividends, or rather high ratio div/interest where dividends are pushing prices up and interest rate does not push them up, but why there is that "overhead" in short dtes in the first place? It is not probability skew (I think) because, if so, combo prices would increase with time. But maybe, again, there is that play - int, div, probability - in action. I'm not convinced. Wonder if anybody already took closer looked at that.
Likely it is something simple I've overlooked.