

I saw something briefly about Amy's Time Zone Trade at SMB. The thing I wondered about was Ron Bertino's Weighted Vega. If you remember, Ron showed how Calendar Spreads are essentially Vega neutral. The Time Zone Trade apparently uses a Calendar spread to give the position a positive Vega.
Here's how to calculate Weighted Vega:
https://forums.tradingdominion.com/...-that-weighted-vega-capdisc-presentation.109/
I found an interesting PDF that delves into Weighted Vega deeper:
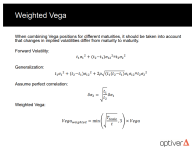
http://www.topquants.nl/wordpress/w...5/01/Van-Gulik-Risk-management-at-Optiver.pdf
Mark Sebastian also talked about it in this old now-defunct options trading e-zine:
http://www.snifferquant.com/gyantal.../ExpiringMonthly/expmonthly_vol2no8_oct_1.pdf
I haven't seen the full trade so perhaps I'm missing something. Has anyone seen the full Time Zone Trade?
Opinions?
Here's how to calculate Weighted Vega:
You can easily calculate this: Weighted Vega = Vega x SQRT(30/DTE). This normalizes the Vega of any expiration to a fictitious expiration of 30 DTE. While 30 is typically used, you can use other normalizing factors as well.
https://forums.tradingdominion.com/...-that-weighted-vega-capdisc-presentation.109/
I found an interesting PDF that delves into Weighted Vega deeper:
http://www.topquants.nl/wordpress/w...5/01/Van-Gulik-Risk-management-at-Optiver.pdf
Mark Sebastian also talked about it in this old now-defunct options trading e-zine:
http://www.snifferquant.com/gyantal.../ExpiringMonthly/expmonthly_vol2no8_oct_1.pdf
I haven't seen the full trade so perhaps I'm missing something. Has anyone seen the full Time Zone Trade?
Opinions?

