T
TiborK
Guest
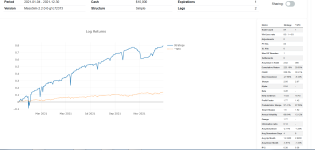
Here is an example run where PT is specified as function of credit received:Hmm... I am not sure how setting the profit target on the underlying would work
I mean in case of a theta decay the underlying should not have to move in order to make profit
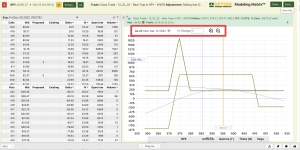
How would I change it to make it based on the credit received ?
The ProfitTarget is specified as:
"100 * (leg_pds_short_price * leg_pds_short_qty + leg_pds_long_price * leg_pds_long_qty + leg_pcs_short_price * leg_pcs_short_qty + leg_pcs_long_price * leg_pcs_long_qty)"
The 100 multiplier is required to account for the number of underlyings controlled by one option.