Update Schwalbe trade

  • Thread starter Thread starter Ignatz
  • Start date Start date
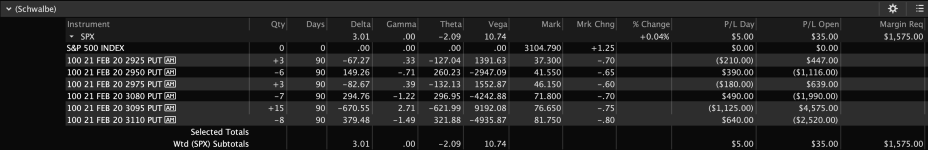
a Member recently opened Igi’s Feb 21 SPX trade in a TOS portfolio margin account and the current margin seems pretty reasonable: $1,575. While this will change when we make adjustments, portfolio margin seems to be the way to go for this trade.

Igi, thanks for sharing. Is this for a 1/2 sized trade for SPX vs /es or is this full size SPX -7/15/-8, etc.,?
 
as he said it´s for a full size trade for SPX.
the reason why it´s so low is the tight V of 15 points although its peak is down about 11k
 
Very good. I like the change you made to V of 15 points wide. Thx.
 
Bryan, Igi is right -- this is for the full size SPX -7/15/-8 + 3/-6/3 trade. I'm happy to report how the margin is changing as we're making adjustments.
 

Attachments

  • spx-schwalbe-11-22-19.png
    spx-schwalbe-11-22-19.png
    181.1 KB · Views: 30
i still try to find some smart adjustments to my trade without changing strikes or capital invested.
here we go:
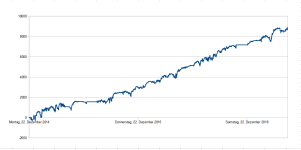
this is the backtest as known:
30 breit V flach.PNG
 
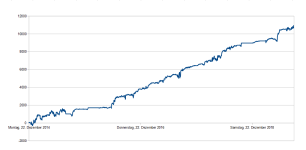
and this is the slightly modified version
same investment, more profit, still same or even less risk.
Adjustments for A are still the same as before, only some changes in V
30 breit V später.PNG
 
Igi, this is a nice improvement. What change did you make to the V to achieve this?

I haven't had a chance yet to backtest your strategy. How much of the results depend on your quarterly start date and trades? In other words, what if you started this trade on different days. For example backtested doing a trade every month? How would it perform before during challenging times like the end of 2018, etc. when the market was dropping dramatically?
 
It's nice indeed the new sea of death is 30 wide instead of 50, but I keep thinking that strikes multiples of 25 have more open interest and volume. I wonder whether the real prices for the adjustments in the new setup can be similar to what backtest have shown. Is the reduction from 50 to 30 worth the risk of not finding enough liquidity?
 
@Bryan Doyle : i trade no overlapping trades and i need 5-strikes in Emini. That´s why i only use quarterly options in Emini. But in the 5 years backtest there were 3 events of bigger Drawdowns. So i already tested it.
My strategy has NO problem with an increase of Volatility, my t+0 is always pretty flat so that´s why i think the performance will not be quite different.
@Michael B : the reduction from 50 to 30 is really worth it because the drawdown during a trade´s life is significant reduced when the price is in or below (!) the "V". In the quarterly options there is still enough liquidity.
 
Igi, what I am wondering is since you only use quarterly options in live trading (I understand why) does this give you a large enough sample size in backtesting for all the various challenging situations? How many trades have you been able to backtest? So maybe we test different start dates and loosen up on the 5-strikes for the backtesting just to ensure it is very robust in challenging markets. But maybe you did this already in your backtests?
 
hi Bryan my trades always starts on monday after 3.friday quarterly. they start in low, middle and high volatility, in an uptrend, sideways, downtrend.
no matter what the circumstances are, the main argument for my robust system still is: flat t+0, no fat tail risk.
2015 was a challenging market, 2018 was a challenging market.
And i tested different start dates but as i said: i dont like overlapping trades.
 
I am probably not explaining myself well. I do really like your trade design with no fat tail risk, no adjustments to the upside, etc.

If you start on monday after 3rd friday then over 10 years that is just 40 backtests, so a small sample size. Or have you backtested other start dates (even though you would not trade these dates live)? If yes, how many tests? Thanks.
 
my point of view is not: test as many as possible, but BE PREPARED as good as possible.
the ugly moves of 2015 and 2018 were more violent than all moves before. Lehman 2007: 18 months from the top to the bottom
2015 Flashcrash: 1 month to the bottom 2018 Volacrash: 8 days Sept 18: 3 months from top to bottom.
The faster the move the more dangerous it is. Moves are really getting faster and i always ask me: WHAT IF.....
so being prepared is the key and not testing as much. IT´S ALL ABOUT RISK.
being prepared is the key to still be able to trade in the future. This also means having a possibility to make useful adjustments WITHOUT adding money.
And NO Fat Tail Risk and resilent against volatility is the most important key to make consistent profits.
Markets change, volatility change and some other things.
i think: be prepared for the most ugly situation and you will survive, whatever will happen.
 
Igi, is there a link to sign up for the Monday meeting?
Thanks.
 
Top
Contact Us