How to calculate put option price using put/call parity

status1

Well-known member
I watched the recent options 101 group meeting where there was a discussion about put call parity and how to calculate the price of an ITM call option
I was wondering if that can be done if the bid price is 0 ?
Looking at a stock that has low volume and open interest the bid was showing 0 for both put and call

The stock price at the moment is 19.66 so the 19 strike price has an intrinsic value of 0.66
The 19 strike call bid price is 0 and the ask is 0.85
The 19 strike put bid is 0.05 and the ask is 0.15 at the moment but a few days ago it was 0 bid 2.0 ask when the stock was around 19.51
There is 22 DTE and the iv of this expiration is 18.95%

How do I know what is the right price for the put ?
 
Should be able to calculate it based on the ask prices. You need to know:
- Underlying price (stock, index, futures etc)
- Strike price
- Call price (use the ask price)

Put price = Strike price - Underlying price + Call price

for your example:

Put price = 19.00 - 19.66 + 0.85 = $0.19
 
Hmmm...
Is that the mid price where it should fill or the ask price ?

Interesting but I doubt I will get that much for the put
Normally that would probably be correct calculation but as I said the bid is 0 so it probably means the ask is not correct either for the put and the call
Currently the ask for the put is 0.10 so I doubt I would get filled at 0.19

The stock price has moved up to 19.79 and the ask for the call is at 1.05
So using the same calculation
Put price = 19.00 - 19.79 + 1.05 = $0.26
Looks like it's going in the wrong direction the further the 19 put moves OTM the more expensive it is
I guess the calculation only works if the bid ask prices are correct
 
Status1, maybe I'm jumping ahead of Tom, but I think you have it backwards.
Typically you use put-call parity to figure out price of less liquid option or option that has a price that looks suspicious.

In your example you have ITM call with wide bid-ask spread and OTM put with narrow spread. Thus call price is 'suspicious' and you want to find out what that price might be.Not the other way. You suspect that price of call is somewhere between 0 and .85 (but not necessary).
Put spread is .05x.15, so it is much more precise so you should use this one to calculate the other.

Let's do it.
(Befor you start calculations make some effort to verify the price of a put. For example look at neighbor prices to see if 0.15 is not sticking out.)

Simplified formula is: CallPrice - PutPrice = Spot - Strike
filling in:
CallPrice = (19.66 - 19) + 0.15 = 0.81
so, if you use MID price in your order you may sit in frustration for hours that you are not filled even .20 above...

if price move as you said in second post we will have:
(I assume put price dropped to .10)
CallPrice = (19.79 - 19) + 0.10 = 0.89

Now if you figured out that CallPrice, 1.05, is the correct one, then you can calculate PutPrice from it:
PutPrice = 1.05 - (19.79 - 19) = .26
Second example might confuse you a little but if you are interested you spend some time and figure it out.
Good way to understand this is to plot it on paper. Use your knowledge about synthetics.

I used simplified formula, that you can do calcs in your head. If using spreadsheet you may want to use forward price instead of Spot.

How useful is put-call parity formula this days? Depends what and how you are trading. I stick to OTMs and don't use c-p parity but if checking all prices becomes your second nature you may save some $$ from time to time.
Myself more often I look at OTM / ITM spread prices before placing orders. Not as often as I should though...
 
Status1, maybe I'm jumping ahead of Tom
No problem I appreciate the help
In your example you have ITM call with wide bid-ask spread and OTM put with narrow spread. Thus call price is 'suspicious' and you want to find out what that price might be.
It's not so much the wide bid ask spread as there is no bid at all so both the call and the put are suspicious
There is a bid now but a couple of weeks ago when I wanted to enter the trade there was 0 bid on both sides
Perhaps a few screenshots may help
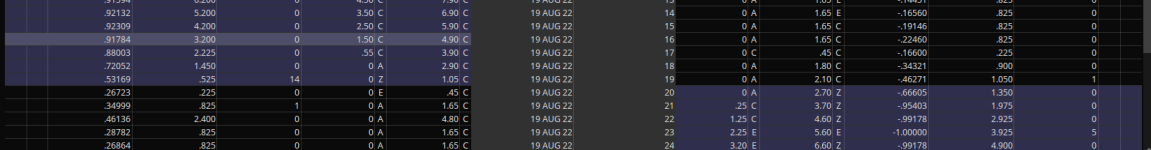
Example 1 at 19.16.PNG
I used on demand to go back in time to the date I placed the trade which was on 7/14/2022 The price was 19.16 at the time in the morning
Notice that both the put and the call have 0 bid
How would you make the calculation in this case ?


Example 2
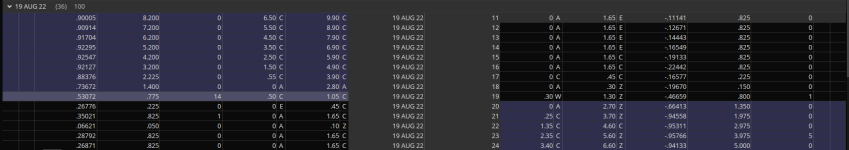
Example 2 at 19.14.PNG
This was on the same day a few minutes later with the price at 19.14
Notice how now there is a bid on both sides now
That's not because the market makers added it it's because I placed an order to sell a put at 19 There was 0 volume I was the only one in this underlying I placed an order to sell at 1 which was the mid in the first example and I was pretty sure it's not going to be filled than later on in this example I lowered the price to 0.80 cents but still did not get filled
I think Scott or someone else mentioned that the bid /ask prices are done by auto quote so that's why you see those bid ask prices
So even at this point with the wide but not 0 bid the option prices are still suspicious on both sides because that is based on the auto quote not the real market so I am not sure if it can be calculated


Example 3
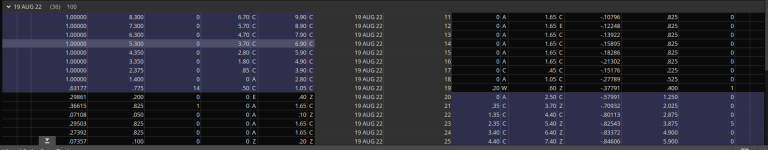
Example 3 at 19.49.PNGThis was again a few minutes later after I kept lowering the price while the underlying went up to 19.49
I got down to 0.50 cents but it was still not getting filled for the entire lot Than I just placed 1 lot and it got filled on that and added a few more and those got filled also than added more but it would no longer fill so I ended up lowering the price to 0.40 cents and I was filled at that price
Notice that the put bid/ask from example 2 at 0.50/1.05 did not change in example 3 while at the same time I lowered my price from 0.80 to 0.40 to get filled


I tried to get filled at the same price in a different account but It would no longer fill at 0.40
Another interesting thing is after I got filled the bid/ask went back to 0/2.0 which messed up the p/l
So if there is no active open order I guess the auto quote just adds in some bogus numbers just to have something on the screen
So I left that order in the other account at GTC with the 0.40 price just to keep the p/l in the ballpark but it never got filled

Another observation I noticed was that I was the only one that generated the volume for that day but the open interest is not updated until the next day so there is a 1 day delay between the volume and open interest numbers at least for this underlying
 
Those are different, but related, issues. I tried to explain how to calculate prices using put-call parity. For tips how to figure out price when options chains seem to be flawed - look at other material on Aeromir or other places. Maybe as Tom to do practical exercise on one of 101 sessions.
If you don't have reliable price for put or call you can not calculate parity.

Your observation about OI are correct. The numbers show EOD values.
 
Top
Contact Us